The Blind Spot
Financial institutions are not ignoring elder financial exploitation. To suggest otherwise would be inaccurate and unfair. Banks, brokerages and regulators have developed safeguards to identify and interrupt suspicious activity involving older customers.
FINRA Rule 2165 permits member firms, under specified conditions, to place temporary holds on transactions or disbursements when they reasonably believe financial exploitation of a specified adult has occurred, is occurring, has been attempted or will be attempted. FINRA Rule 4512 requires reasonable efforts to obtain trusted-contact information for noninstitutional accounts. Federal regulators have also identified employee training, suspicious-activity reporting, referrals, legally appropriate holds and coordination among institutional functions as potential responses.
These mechanisms are real. Their reach and limits deserve careful examination.
FinCEN examined reports covering the year ending June 15, 2023, and identified 155,415 reports associated with approximately $27 billion in suspicious activity involving elder financial exploitation. The $27 billion is not a tally of confirmed losses; the reports can concern attempted as well as completed activity. AARP has separately estimated $28.3 billion in annual losses using a different method. These figures should not be added together or treated as equivalent measurements.
What can those reports tell us? And what can they not tell us?
Financial institutions can examine transaction amounts, frequency, recipients, locations, devices and departures from established patterns. Which forms of exploitation are those signals especially well equipped to identify? Which forms, if any, are harder to discern?
Consider several ordinary circumstances: a daughter accompanying her mother to financial appointments; a caregiver managing bills; a new friend becoming important after a spouse's death; a professional charging more for services; or an agent acting under a valid power of attorney.
None establishes wrongdoing. A daughter may be devoted. A caregiver may be indispensable. A widow may fall in love. An older person may choose to give away money that others expected to inherit.
What information, beyond the mere presence of these relationships, would justify concern? What evidence might distinguish assistance from coercion without treating dependence, grief, age or generosity as proof of incapacity?
Identity authentication asks whether the person or credentials are genuine. Examining the exercise of entrusted authority raises a different question: whose wishes does a decision reflect? How often can institutions answer that second question, and how often is it beyond what their systems or responsibilities can reasonably establish?
A password may be correct. A signature may be genuine. A power of attorney may be valid. Those facts matter; none alone resolves every question about influence. Equally, their presence does not imply exploitation.
What, if anything, might transaction-focused safeguards fail to recognize? Where are their limits appropriate? And where might additional inquiry do more harm than good?
Protecting The Transfer
What does it mean to protect someone's wealth? Is the goal to prevent unauthorized activity, preserve assets, respect lawful instructions, sustain independence, or some combination of these?
These objectives often reinforce one another. Under what circumstances might they conflict?
Families, caregivers, attorneys and financial advisers frequently provide valuable assistance. Consider an older woman who, after her husband's death, asks a relative to manage household bills. The arrangement works. Over time the relative handles appointments and communications as well.
Perhaps the woman prefers this arrangement and remains fully in charge. Perhaps her wishes evolve. Or perhaps she begins to feel unable to disagree. What would distinguish these possibilities? Who is positioned to ask, and what gives that person the right to intervene?
An older adult retains the right to make unconventional, generous, unpopular or financially unwise choices. Disagreement from prospective heirs does not establish exploitation. Neither should respect for autonomy prevent proportionate attention to credible indications of coercion.
How can both principles be honored without assuming that a particular answer is inevitable?
Whose Interests?
An owner may seek independence. Family members may hope to preserve an inheritance. A caregiver may rely on compensation. An attorney may follow lawful instructions. A financial institution may balance customer protection, privacy, compliance and service.
Must those interests conflict? When might they align? When they diverge, what principles should govern decisions and whose authority should be decisive?
A trusted contact may provide helpful context. What safeguards address the possibility that the contact is mistaken or conflicted? A temporary hold may prevent loss. What safeguards address the possibility that a legitimate payment is delayed? A power of attorney can enable essential care. How can the principal question its exercise or revoke it when legally entitled to do so?
How should the costs of intervention be weighed against the costs of inaction? What opportunity exists for review, correction and appeal?
What Can Reasonably Be Known?
What evidence would support a conclusion that an instruction reflects someone's independent choice? What would count against it? Can a professional determine that reliably from a transaction alone? When is direct conversation appropriate, and when might it be intrusive or unsafe?
How should an institution distinguish voluntary reliance from constrained choice without treating disability, age, grief or dependence as incapacity? What limits on observation, privacy and professional competence ought to be respected?
Perhaps an institution can sometimes establish authorization but not the full social context of a decision. Does that mean a safeguard has failed, or that it has fulfilled its proper function? What additional safeguards, if any, could help without creating a new source of control over the owner?
What should success mean: fewer financial losses, more effective interventions, greater ability to challenge mistaken interventions, preserved participation in decisions, or some balanced measure of all four?
Before We Call It A Transfer
The Great Wealth Transfer is often discussed in terms of generations, beneficiaries and trillions of dollars. Before wealth becomes an inheritance, however, it belongs to someone living with choices in the present.
Those choices may concern family, generosity, risk, independence or the possibility of remaining in a cherished home.
How might protection of assets support the owner's freedom? Under what circumstances might a measure intended to protect an eventual transfer interfere with the owner's present wishes? And who should be accountable for resolving that tension?
Are we asking enough about the person whose wealth is being discussed, before asking where the wealth will go?
The Canary'S Return
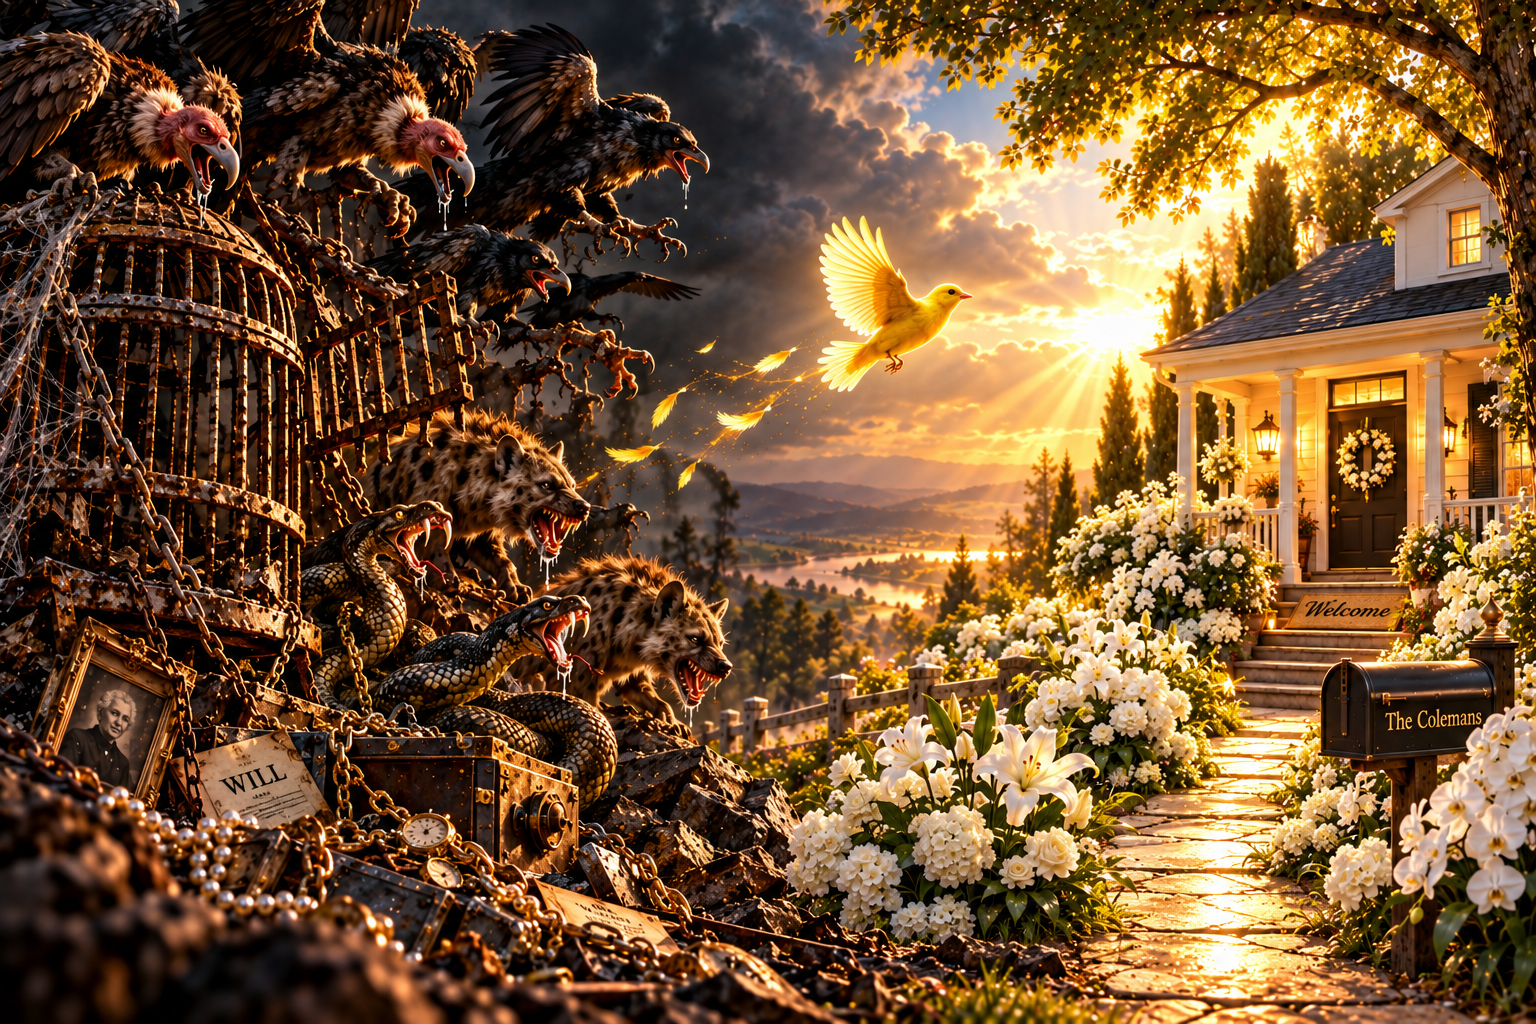
We began with Maria Coleman. It seems fitting that we return to her.
Maria is in her third year of mourning Don, her husband of nearly six decades. She currently resides at Lockwood of Burton, away from the home they shared in Flint, Michigan.
She wants to return home.
Maria purchased that home in her own name because racial discrimination prevented Don, a Black American serviceman, from purchasing it. The home carries a history of love, sacrifice and belonging that no account balance could capture.
Her VA survivor-benefits matter remains unresolved. The Department of Veterans Affairs lists age 85 or older as a basis for requesting priority processing through VA Form 20-10207. Maria will turn 91 in late January 2027.
What does waiting mean when time cannot be recovered? What does returning home mean to the person who wishes to do so? What obstacles stand in the way, and which, if any, could the responsible parties reasonably remove?
When families, professionals and institutions speak of protecting someone's interests, how do they determine what that person actually wants?
The Great Wealth Transfer may be measured in trillions of dollars. Should its human consequences be measured only in dollars? What would a fuller account include?
Maria Coleman was never the headliner. She was the canary in the coal mine.
And the canary just wants to return home.
How much longer should a woman approaching 91 have to wait for a resolution to her survivor-benefits claim?
And who is willing to help?
Some may ask, with so many canaries out there, why does Mrs. Maria Coleman matter?
Because I met her only once. Because I've spent thousands of hours speaking with her since.
And because I give a damn.
Sources & References
[1] FINRA Rule 2165, Financial Exploitation of Specified Adults. https://www.finra.org/rules-guidance/rulebooks/finra-rules/2165
[2] FINRA Rule 4512, Customer Account Information. https://www.finra.org/rules-guidance/rulebooks/finra-rules/4512
[3] FinCEN, Financial Trend Analysis: Elder Financial Exploitation (2024). https://www.fincen.gov/news/news-releases/fincen-issues-analysis-elder-financial-exploitation
[4] AARP Public Policy Institute, The Scope of Elder Financial Exploitation: What It Costs Victims (2023). https://www.aarp.org/pri/topics/work-finances-retirement/fraud-consumer-protection/scope-elder-financial-exploitation/
[5] Federal Reserve and partner agencies, Interagency Statement on Elder Financial Exploitation. https://www.federalreserve.gov/frrs/guidance/interagency-statement-on-elder-financial-exploitation.htm
[6] U.S. Department of Veterans Affairs, VA Form 20-10207, Priority Processing Request. https://www.va.gov/forms/20-10207/